
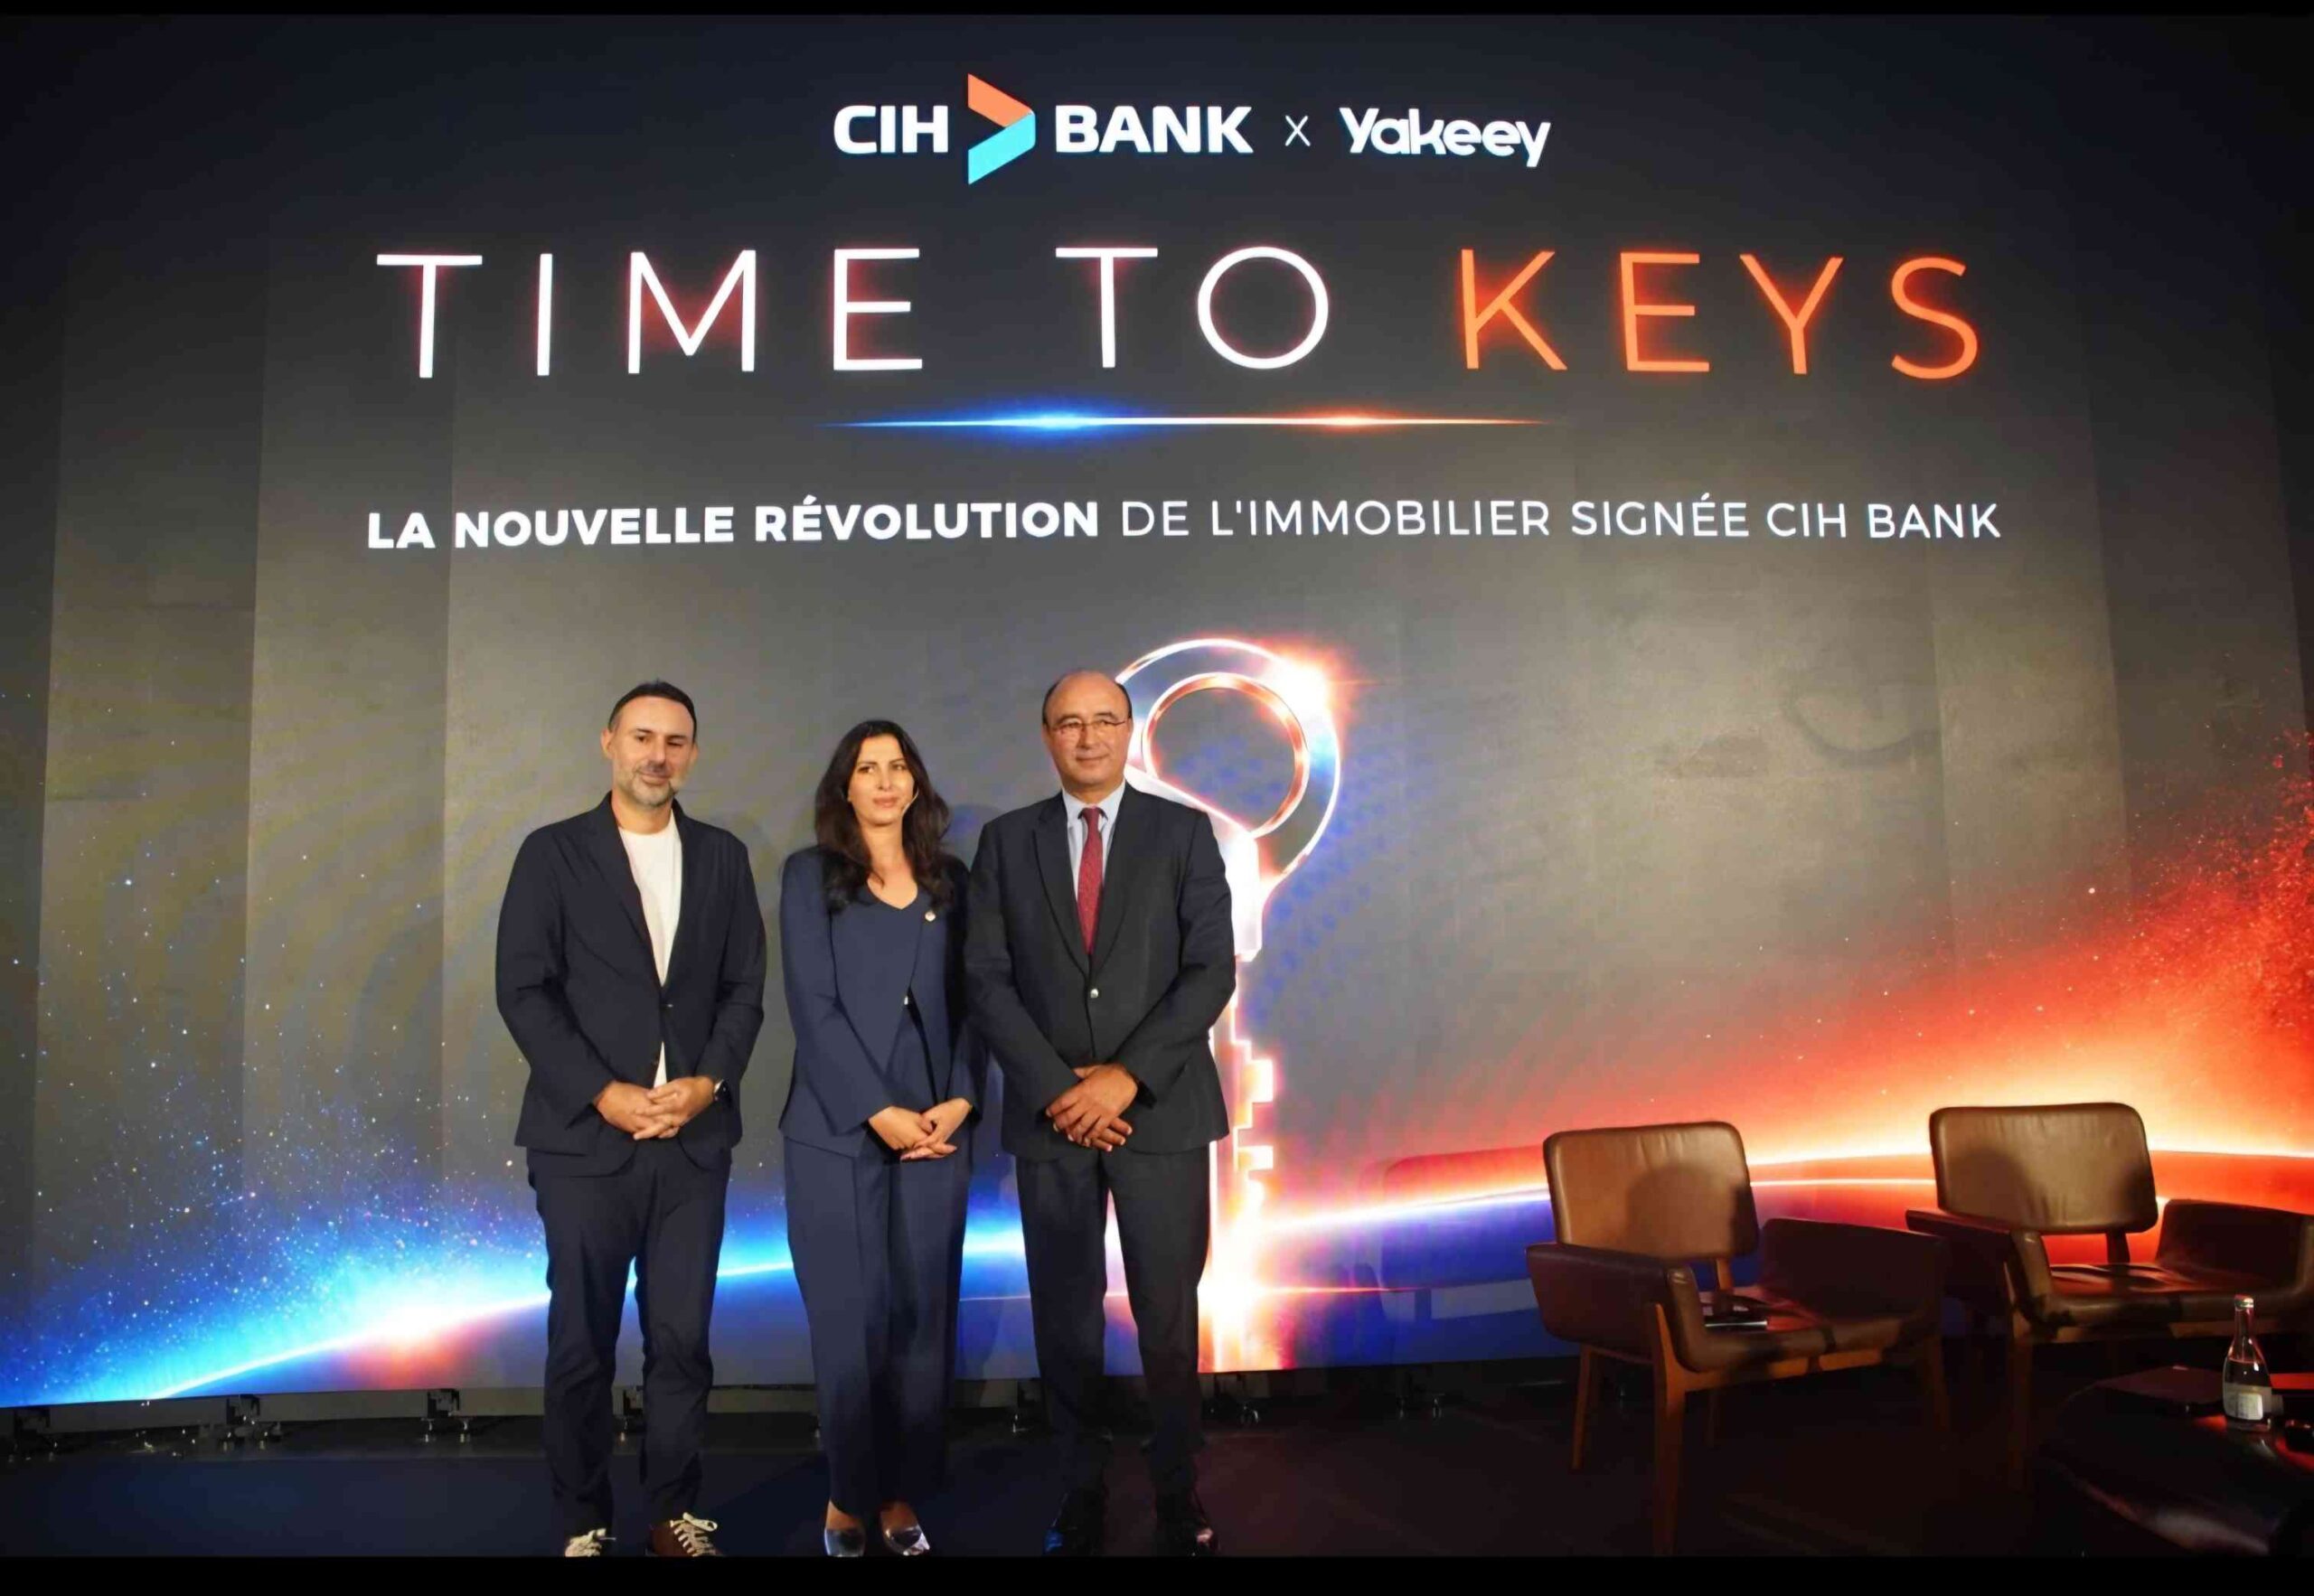
Buying a home can mean searching through property listings, visiting banks and trying to work out how much you can afford to borrow. A new service from CIH Bank and property platform Yakeey aims to bring these steps together in one mobile app. The service allows customers to search verified property listings through the CIH Mobile app and submit mortgage applications online.
The partnership aims to make it easier for buyers to find a home and explore their financing options without having to move between different platforms.
“Over time, CIH Bank has evolved its offer to respond to changes in lifestyles and new customer expectations,” said Amal Mouhoub, the bank’s deputy general manager for communication and strategic marketing. “Today, our Bank continues this ambition by facilitating access to housing and offering solutions that are simpler, more accessible, and tailored to everyone’s needs.”
Karim Beqqali, chief executive and founder of Yakeey, said buying a home often involved separate and uncertain processes for finding a property and securing a loan.
“In Morocco, buying a home still too often feels like an obstacle course: you look for a property on one side, financing on the other, without ever being sure of anything,” he said. “With CIH Bank, we are finally bringing both together in an application that customers already have in their pocket. Finding the right verified property and immediately knowing that you can finance it—it is this peace of mind that we want to offer every Moroccan.”
Yakeey’s technology and expansion
Founded in Casablanca in March 2023, Yakeey operates an online property marketplace supported by more than 800 certified real estate advisers through its YakeeyPro network.
Its Yakival tool estimates property values using data from completed transactions rather than relying only on advertised prices.
The new service is intended to bring property searches and mortgage applications together, reducing the need for buyers to handle each process separately.
The partnership also includes joint support teams to track applications, help buyers with notary procedures and address delays in processing loans. The service is designed to handle more complex purchases, including cases where buying a new home depends on selling an existing property.
Yakeey recently raised $15m in a Series A funding round, described in the supplied information as the largest property technology funding round in the country to date.
Investors include Enza Capital, the International Finance Corporation, the private-sector arm of the World Bank Group; Egypt’s Beltone Venture Capital; and CDG Invest, a state-backed Moroccan investment fund.
The company plans to use the money to expand its adviser network, improve its artificial intelligence-powered pricing tools and develop more partnerships with banks.
Eight-part television series
CIH Bank and Yakeey are also producing Chkoun Yl9ali Dar, which translates as “Who Will Find Me a Home?”
The eight-episode series will air during prime time on national television channel 2M, with Tuesday evenings specified in the supplied background.
It will follow families as they assess properties, learn about notary fees, explore housing assistance and seek bank approval.
The programme is intended to help viewers understand the financial and administrative steps involved in buying a home, alongside the launch of the digital service.
The launch comes as the government runs its Daam Sakane housing assistance programme, which covers the period from 2024 to 2028.
The scheme offers a grant of 100,000 dirhams (about $10,000) to eligible buyers purchasing a home costing no more than 300,000 dirhams. Buyers of eligible homes priced between 300,001 and 700,000 dirhams can receive 70,000 dirhams (about $7,000). Properties costing more than 700,000 dirhams do not qualify.
The grants are designed to reduce the amount buyers need to save before purchasing a home.
Banks generally ask buyers to pay 10% to 20% of a property’s price themselves, although requirements vary and some borrowers may qualify for more generous financing.
For example, a buyer purchasing a home for 500,000 dirhams would normally need a 100,000-dirham deposit if the bank financed 80% of the price. A 70,000-dirham housing grant could reduce the buyer’s contribution to 30,000 dirhams, excluding notary fees and other costs.
Under another possible arrangement, a bank could finance the remaining 430,000 dirhams, equivalent to 86% of the property’s price, if the buyer met its affordability requirements.
Applicants must register through the official Daam Sakane website, daamsakane.ma, and meet the programme’s conditions. These include not owning a primary home in the country and not having previously received state housing assistance.
After preliminary approval, which the supplied information says typically takes about seven days, buyers select a property and obtain a preliminary sale agreement. The bank can then assess the mortgage application and account for the grant.
The state transfers the grant to an account held by the appointed notary at the Caisse de Dépôt et de Gestion (CDG). The bank sends the mortgage funds to the same notary, who pays the seller and registers the property. The supplied information says a 10-year state restriction on resale applies.
Bank Al-Maghrib, the country’s central bank, has maintained its key policy rate at 2.50%.
Fixed mortgage rates are reported to range from 3.90% to 5.50%, depending on the borrower’s financial profile and the length of the loan. Mortgage terms can extend to 25 years.
Banks generally limit monthly debt repayments to between 40% and 50% of a borrower’s net income, depending on their circumstances, salary level and employment status.
Lower borrowing requirements can make a difference to household budgets. The supplied figures estimate that a mortgage of 360,000 dirhams, repaid over 20 years at an annual interest rate of 4.50%, would cost about 480 dirhams less per month than a 430,000-dirham loan.
Civil servants and employees of large companies may qualify for more favourable lending arrangements. Some schemes can cover the full property price, subject to the lender’s conditions.


