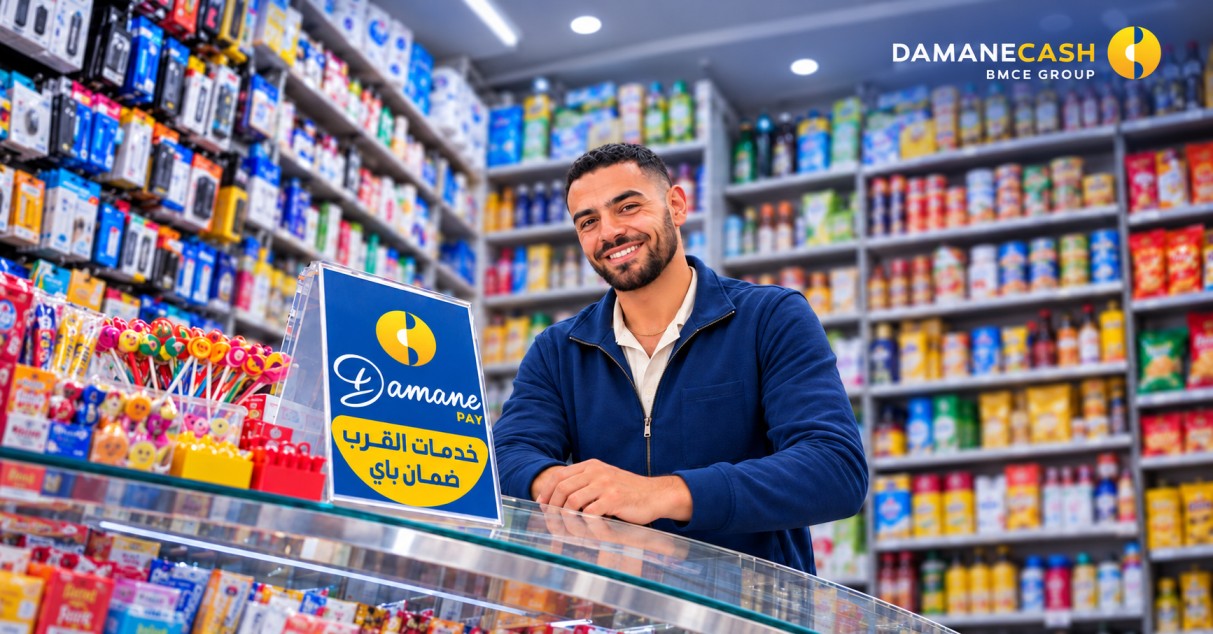
A neighbourhood shop could do more than sell groceries or stationery. It could also help people pay their bills, top up their phones and send or receive money, while earning extra income for its owner. That is the opportunity Damane Cash is promoting as it seeks to recruit more local businesses into its Khadamat Damane Pay network, which already has 5,735 service points across Morocco.
The scheme allows local retailers, including grocery shops, kiosks, stationery shops and cybercafés, to offer everyday payment services. These include water, electricity, internet and telecom bills, as well as mobile phone top-ups.
Depending on the services available at each outlet, merchants can also handle cash deposits and withdrawals through the Damane Pay mobile wallet, and help customers open basic payment accounts.
In return, shop owners earn a commission on each eligible transaction. The extra services may also bring more customers into their shops, potentially increasing sales of their usual goods.
Khadamat Damane Pay turns existing shops into local payment points, allowing customers to carry out basic financial transactions without having to visit a dedicated payment agency or bank branch.
Services can include bill payments to utility providers such as REDAL, Lydec, Amendis and ONEE, as well as internet and telecom bills and certain national or local taxes and duties.
Customers can also top up their mobile phones, deposit money into or withdraw cash from their Damane Pay wallets, and apply to open basic payment accounts.
The most basic, or Tier 1, accounts described in the scheme have a limit of 200 dirhams.
Transactions are processed through a payment terminal or a dedicated application, depending on the arrangement provided to the retailer.
Using existing shops allows payment providers to reach neighbourhoods where customers may have limited access to traditional bank branches. It also gives small retailers another way to earn money from their premises and attract regular visitors.
The approach supports a wider push to extend access to financial services, particularly in rural and underserved areas, while moving some routine payments from cash-based processes to digital systems.
Banking Law No. 103-12 established the legal framework for payment institutions, allowing authorised non-bank providers to offer payment services and open payment accounts. Bank Al-Maghrib and the Ministry of Economy and Finance have also supported efforts to widen access to financial services through national financial inclusion policies.
How can merchants join?
Businesses interested in becoming authorised Khadamat Damane Pay retailers can apply through Damane Cash’s website:
They can also contact the company by phone on 05 20 26 26 26 or email [email protected].
Applicants generally need a physical commercial premises, valid commercial registration or an appropriate professional status, such as a patente or auto-entrepreneur registration. They also need access to a smartphone, tablet or internet connection, depending on the equipment required.
Damane Cash reviews applications and checks the proposed shop location, including to avoid overlapping outlets in the network. The application process is reported to typically take about 72 hours, although this may vary.
Once approved, merchants receive access to the payment platform or terminal and guidance on processing transactions, managing cash balances and meeting basic compliance requirements.
The company is inviting interested retailers to complete its online form and register their interest in joining the network.
Damane Cash is an authorised payment institution regulated by Bank Al-Maghrib, the country’s central bank. It is a subsidiary of Bank of Africa, formerly known as BMCE Bank, and operates within the group’s financial services business.
Beyond Khadamat Damane Pay, the company offers domestic and international money transfers, including services through Western Union, Ria and MoneyGram. It also provides digital payment accounts, mobile wallet services and cash-in and cash-out transactions.